A formal RFP can bring transparency, structure, and competition to outside counsel selection. But not every matter calls for one.
Some engagements are significant enough to justify a competitive sourcing process. Others need counsel selected quickly. Some involve work a trusted firm already knows well. Others simply do not warrant the time and effort of a formal RFP.
Just because you’re not running an RFP doesn’t mean you’re skipping the evaluation.
Whether a legal team is running a formal sourcing process or deciding which firm should handle the next matter, the same fundamental question remains: Why is this the right firm for this work?
Too often, the answer comes down to familiarity, relationships, or whoever handled something similar last time. Those factors can matter, but legal departments already have another source of evidence available to them: their own matter, spend and vendor performance data.
The opportunity is to use that information not only during an RFP, but every time outside counsel is selected.
When does an outside counsel RFP make sense?
There is no reason to force every matter through the same sourcing process.
Formal RFPs can be particularly valuable when a legal department is selecting counsel for high-stakes work, evaluating multiple firms for a significant engagement, refreshing a broader panel, or simply getting an update on firms’ evolving capabilities. A structured process gives the team a consistent way to gather information, compare approaches to managing a case, and evaluate firms on more than familiarity or hourly rates.
But a formal RFP also requires time from the legal department and the participating firms. For many routine or lower-risk matters, the process may be more than the decision requires.
The goal should not be to run more RFPs. It should be to make better outside counsel decisions. That starts with a clear view of when an outside counsel RFP makes sense and when a lighter-weight process will serve the matter just as well.
What should you evaluate when you aren’t running an RFP?
A legal team may decide not to issue an RFP, but you can still evaluate your options.
Before assigning a matter, consider what your existing data can tell you about the firms you already work with:
Which firms have handled comparable matters?
Past matter records can show which firms have experience with similar types of work, jurisdictions and levels of complexity.
That provides a more useful starting point than simply asking which firm is top of mind.
What did similar work actually cost?
Historical spend can help legal teams understand what previous matters cost and how different firms performed against expected budgets.
The question is not simply which firm has the lowest rate. It is which firm has demonstrated value on comparable work.
How did the firm staff the work?
Two firms may approach the same matter very differently.
Historical staffing data can help show whether previous engagements used the right mix of partners, associates and other resources for the work involved.
Did the firm stay within budget?
A proposed budget is useful. A history of how a firm performed against budgets provides another layer of evidence. Does one firm tend to be more accurate in their initial case assessment, and therefore expected costs, while another typically has multiple budget revisions for each engagement?
Consistent budget performance can help a legal team assess predictability before assigning new work.
Were there recurring billing or compliance issues?
Invoice history may reveal patterns that are easy to overlook when matters are considered individually.
Repeated guideline violations, staffing issues or billing adjustments can provide useful context when deciding whether a firm is the right choice for another engagement.
What happened after the matter was assigned?
Assigning outside counsel to a matter is just the beginning, not the end. Having a governance process based in effective communication to manage and evaluate performance throughout the engagement is a critical metric of success.
Where legal teams capture relevant outcome and performance information consistently, that data can help inform the next matter, the next panel review and the next RFP. In fact, matter and spend data can reveal how firms actually performed long before a formal RFP ever enters the conversation.
Relationships still matter. Data makes them more useful.
Legal work is not a commodity, and outside counsel selection should not become a spreadsheet exercise.
A general counsel may know that a particular partner understands the business exceptionally well. An in-house attorney may have years of experience working successfully with a specific firm. A legal operations team may know that certain firms collaborate better with internal teams than others.
Those are meaningful inputs.
The problem comes when relationship knowledge is the only input or when important experience lives only in the memories of individual team members.
Structured matter and vendor data gives legal teams a way to complement that judgment with evidence.
Instead of asking, “Who do we usually use?” the conversation can become:
Who has done this type of work before?
How did they perform?
What did it cost?
Did they meet expectations?
What have we learned from working with them?
Has another firm’s capabilities evolved where they warrant consideration?
Are the lawyers who typically do the work at our preferred firm still there, or have they moved on?
That creates a more informed decision without requiring a formal sourcing event every time work needs to be assigned.
Outside counsel selection should be a continuous cycle
One of the biggest limitations of treating RFPs as standalone events is that the selection process can become disconnected from everything that happens afterward.
A firm is evaluated. A decision is made. Then the actual matter, invoices, budget performance and vendor relationship move into other workflows.
The better model is a continuous cycle:
Select → engage → manage → measure → select again
Each engagement should create information that improves the next decision.
Matter history builds a record of experience. Spend data shows what the work costs. Invoice information reveals compliance and billing patterns. Performance information adds context around how the relationship actually worked.
Over time, legal teams can build a more complete view of their outside counsel relationships instead of starting from scratch every time they need to make a sourcing decision.
That same information becomes valuable when a formal RFP is warranted. Rather than relying only on what firms say in their proposals, the legal department enters the process with its own history and evidence: structured vendor performance data that reflects what actually happened, built on systems that connect matter, spend and vendor information instead of leaving it scattered across inboxes and spreadsheets.
Make the process fit the decision
The answer is not to require an RFP for every outside counsel engagement.
It is also not to reserve structured, data-informed decision-making only for the handful of matters that receive a formal sourcing process.
Legal teams need both.
For significant engagements, a structured RFP can help teams compare firms, evaluate value and create a defensible record of the decision. For matters that do not need an RFP, historical matter, spend and performance information can still provide the evidence needed to make a thoughtful choice.
The process may change depending on the matter.
The standard for making an informed decision should not.
Ready to rethink your outside counsel sourcing process?
Explore The Modern Outside Counsel RFP Playbook for a practical framework to determine when an RFP earns its keep, evaluate firms on total value and build a more structured approach to outside counsel selection.
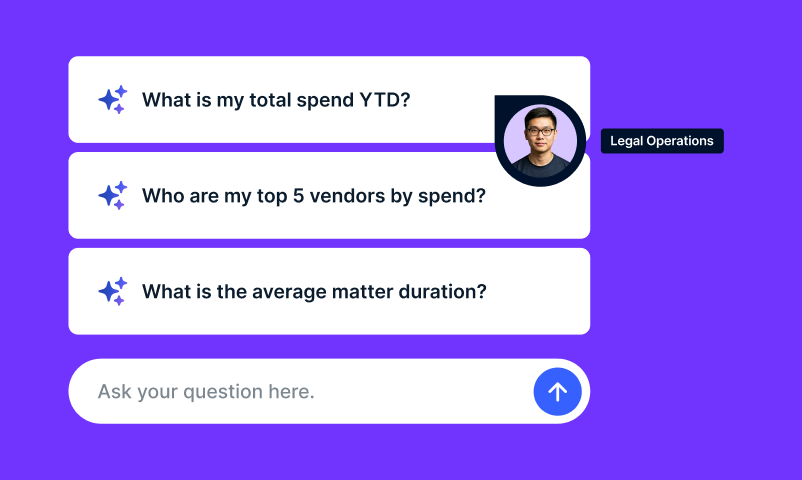
Legal leaders should be able to ask direct questions about spend, budgets, matters, vendors and overall operations, then receive a clear answer while there is still time to act. The standard is not speed alone. The answer should also be accurate – current, grounded in the legal department’s system of record, aligned with the user’s permissions and specific enough to support a decision.
That expectation changes the role of legal data. Instead of becoming a quarterly reporting exercise, data becomes part of day-to-day leadership. The most useful questions fall into three groups: where money is going, where attention is needed and whether the answer can withstand scrutiny.
What is happening with legal spend right now?
Leadership questions rarely arrive on the reporting calendar. Your CFO may ask how accruals are tracking against budget before a forecast meeting. Your general counsel may need to know which matters are driving variance before an executive update. Procurement may want to understand which vendors are associated with the most invoice rejections or adjustments before a review.
Legal leaders should be able to ask:
How is current legal spend tracking against budget?
Which matters and vendors are driving the variance?
How do accrued amounts compare with final invoice spend?
Which invoices are received, on hold, rejected or approved?
Which business units are represented in current matter allocations?
These are not unusual analytics requests. They are routine management questions. When each one requires a report request, an export and spreadsheet reconciliation, the answer can arrive after the decision window has passed. Manual legal reporting also consumes time that legal operations doesn’t have or could be better spent applying to any number of other items already on their plate.
Where should Legal investigate before a problem grows?
Good legal reporting explains what happened. Better access to legal data helps leaders decide what to examine next. A high-level total may be useful, but the next question often carries the real insight.
Legal leaders should be able to ask:
Which vendors had the most rejected or adjusted invoices this year?
Which open matters have active purchase orders?
Which open matters had no invoicing activity during the period?
Which invoice reviewer rules apply to a particular vendor?
How are budgets, accruals and final spend comparing across open matters?
The value comes from connecting financial and operational context. Spend without matter information can hide what is driving the number. Accruals without final spend make reconciliation harder. Vendor totals without rejection or adjustment patterns provide an incomplete view of performance.
The goal is not to replace legal judgment with an automated conclusion. It is to make the relevant governed data easier to explore, so leaders can identify patterns, ask follow-up questions and decide where human review is needed.
Can the answer stand up to scrutiny?
A fast answer is useful only when people understand what it means and where it came from. Legal teams work with sensitive information, different access levels and financial definitions that can change the result. “Spend,” for example, may mean billed spend or final spend after adjustments and taxes. A system should ask for clarification when the request is ambiguous instead of guessing.
Legal leaders should also be able to ask:
Is this answer based on the current system of record?
Does it reflect the permissions of the person asking?
Can the team review the underlying detail?
Can the result be presented clearly in a leadership update?
If the question is unclear or unsupported by available data, will the system say so?
These questions establish a practical standard for governed, conversational analytics: current data, permission-aware access, structured answers, supporting visuals and a clear path for validation. They also keep professional judgment where it belongs, with the legal team.
Make faster answers a leadership expectation
Legal departments already hold information about invoices, matters, vendors, timekeepers, budgets, accruals, allocations and purchase orders. The leadership opportunity is to make that information easier to question without moving it into disconnected tools or rebuilding the same analysis for every meeting.
Ask Unity turns governed Unity ELM data into clear, actionable answers and provides guidance on product-related questions. Users can explore legal spend, matters, vendors, budgets, accruals and other operational data through natural-language questions, then review structured responses with supporting charts and tables. When a request is unclear, Ask Unity prompts the user to refine it instead of filling gaps with speculative output.
Explore the Ask Unity datasheet to see how legal teams can move from a plain-language question to a decision-ready answer inside Unity ELM.
Legal billing guidelines provide an essential baseline for invoice review, but they cannot account for every negotiated rate, fee arrangement or matter-specific exception. Accurate legal invoice review requires both the general guidelines and the engagement terms that apply to the individual matter.
The distinction matters because billing guidelines establish the department’s policy, while engagement documents capture the commercial agreement for a specific piece of work. An invoice may comply with one and conflict with the other. Reviewers need both sources to determine what the organization actually agreed to pay.
Without that complete context, reviewers can miss charges that violate the engagement or dispute charges that were expressly permitted. Either outcome weakens spend control and creates avoidable work for Legal Operations and outside counsel.
What do legal billing guidelines cover and where do they fall short?
Outside counsel guidelines establish the department-wide rules for legal billing. They define what is billable, how time should be recorded, which expenses are permitted, and what supporting documentation firms must provide. They give legal teams a repeatable standard and help firms understand expectations before invoices arrive.
That baseline remains important. Onit’s guide to creating and enforcing legal billing guidelines explains how clear requirements improve consistency, transparency and collaboration with outside counsel.
But a baseline is not the complete agreement for every matter. An engagement may include a negotiated rate, an approved timekeeper, a fixed fee or alternative fee arrangement, a matter budget, or a travel exception. Those terms can change how an invoice should be evaluated for that specific engagement.
Consider a simple example. A matter-level engagement letter caps a partner’s hourly rate at $850, while the vendor’s general billing guidelines do not reflect that negotiated rate. If the firm submits time at $950 per hour, a review based only on the general guidelines may miss the variance. Spend Agent can apply the matter-level rate agreement, prioritize it over the general guidelines and identify the line item that exceeds the agreed rate.
For invoice-review purposes, matter-specific terms should take precedence when the organization has documented and designated them to govern that engagement. Reviewing only the general guidelines leaves the process with incomplete context.
What risks arise when invoice review lacks matter context?
Missing engagement terms create risk in both directions.
First, noncompliant charges may be approved. A rate can exceed the amount negotiated for the matter, an unapproved timekeeper can appear on the invoice or a charge can fall outside the agreed fee structure. If the review process sees only the general guidelines, those issues may appear compliant.
Second, permitted charges may be disputed incorrectly. Pre-approved travel can be flagged under a general restriction, or a fixed-fee invoice can be evaluated as though it were billed hourly. Legal Operations then has to reverse the dispute, explain the mistake and restart the payment process. That creates rework, delays payment and can strain an otherwise productive outside counsel relationship.
The challenge is not simply finding more potential violations. It distinguishes a true billing issue from an approved exception. A system that flags every deviation without understanding the engagement can create noise instead of control.
Onit’s AI Center of Excellence tested large language models and experienced legal invoice reviewers against the same billing-review tasks. The top-performing model achieved 92% invoice-level accuracy and 81% line-item accuracy, compared with 72% and 43% for experienced lawyers. The models also completed reviews 50 to 80 times faster. Importantly, the research found that discretionary human judgment improved reviewer accuracy, reinforcing the value of combining automated analysis with human oversight. Read the Better Bill GPT research.
These findings establish the potential of AI-assisted review, but accuracy still depends on context. A review process cannot consistently apply a negotiated exception if the agreement containing that exception is unavailable to it.
The goal is not to challenge every possible charge. It is to make the right decision using the agreement that actually governs the work.
How does engagement-aware invoice review work?
Engagement-aware invoice review evaluates an invoice against the department’s general legal billing guidelines and the documented terms associated with the matter and vendor. This gives the review process the context needed to recognize negotiated rates, fee arrangements and approved exceptions while maintaining a consistent department-wide baseline.
Legal teams can strengthen that process by:
Identifying where matter-specific billing terms are currently stored
Confirming which documents should govern the review when terms conflict
Associating engagement documents with the correct matter and vendor
Establishing a consistent method for recording approved exceptions
Testing review outcomes against representative matters and invoice scenarios
Determining where automated action is appropriate and where a person should make the final decision
Relevant engagement documents can be added to the matter so Spend Agent can review invoices using both matter-level terms and general vendor billing guidelines. When those sources conflict, the designated matter-level terms receive priority.
The documents must be uploaded and associated with the applicable matter and vendor. Relevant email correspondence is not automatically pulled from a mailbox; it must be captured in a supported document, such as a PDF, and added to the matter.
This is an important governance control. The review is based on the terms the organization intentionally provides and associates with the engagement, rather than assumptions drawn from unstructured communications elsewhere. It also makes the source behind a decision easier for reviewers to inspect.
When Spend Agent identifies a line-item violation, Auto Adjustments can calculate a recommended financial adjustment and present the original amount, the issue, the applicable billing guidance and the recommendation together. Organizations can manage this capability by vendor, reflecting the fact that review requirements and outside counsel relationships are not identical across the panel.
This additional context does not remove human judgment. Legal teams can use Sentry mode when a reviewer should approve or reject a recommended action and Auto mode when automated handling fits the organization’s operating model. This allows teams to expand review capacity while preserving oversight where judgment, invoice value or vendor relationships require it.
Key takeaways
General legal billing guidelines establish the default billing standard.
Matter-level engagement documents capture negotiated terms and exceptions that may change how an invoice should be reviewed.
Using both sources helps prevent missed violations and incorrect disputes.
Engagement context strengthens invoice review without eliminating human oversight.
Legal invoice review works best when every decision reflects the complete agreement, not just the department-wide default. See how AI, business rules and human judgment can work together in engagement-aware invoice review. Watch The Right Invoice: Rethinking Legal Invoice Review to learn more.
The best legal invoice review process does not force every decision through the same layer. Use deterministic e-billing rules for objective checks with no contextual exception, contextual AI when the answer depends on written billing or engagement terms and requires interpretation, and human judgment when a finding is material, ambiguous, or sensitive to an outside counsel relationship.
That division of labor creates a more practical operating model. Each layer does the work it is best suited to perform, while the legal team remains responsible for governance and the final business decision with greater accuracy and less manual effort than before.
Review/Act on findings, worked performed in alignment with goal
1. Use deterministic rules for fixed, objective checks
Conventional e-billing rules remain an important first layer of legal invoice review. They are well suited to binary checks that should produce the same answer every time and do not change based on the matter, vendor, or surrounding documents.
A duplicate invoice number is the clearest example. If two invoices carry the same number, the system does not need to interpret a narrative, compare negotiated terms, or weigh an exception. A deterministic rule can identify the condition efficiently and consistently.
The practical test is simple: Could valid context change the answer? If the answer is no, use a business rule. This keeps stable controls stable and avoids adding complexity where interpretation offers no benefit.
2. Use contextual AI when written terms can change the answer
Not every billing decision is binary. General outside counsel guidelines may prohibit a charge, while a matter engagement letter permits it. An approved rate agreement may supersede a standard rate. A negotiated fee arrangement or travel exception may apply only to one engagement.
These decisions require the reviewer to read multiple sources, understand which terms apply, and resolve conflicts between general and matter-specific guidance. That is where contextual AI review can add value. It can evaluate invoice lines against the relevant written context and surface an explanation for review and is also best positioned to interpret a line item where the coding is not necessarily accurate.
The source hierarchy matters. Matter-specific terms should take precedence when they conflict with general billing guidelines. Relevant engagement documents must also be captured in a supported file, uploaded to the matter, and associated with the applicable vendor. Contextual AI should not be described as automatically retrieving terms from a user’s mailbox.
3. Keep people in control of material and sensitive decisions
Finding a potential variance is not the same as deciding what to do about it. A legal team may need to consider the amount at issue, the clarity of the supporting language, the strategic importance of the matter, and the relationship with outside counsel.
Human judgment belongs at this decision point. Reviewers can determine whether to accept a recommended adjustment, request more information, make an exception, or address a broader pattern with the firm. This is especially important for high-value invoices, ambiguous guidance, and sensitive vendor relationships.
Governance should reflect those differences. For example, Spend Agent gives legal teams vendor-level choices for automated action, human confirmation, or no AI review. Those choices are not maturity rankings. They are controls that should align with risk tolerance, billing guidance, and the relationship involved.
Build a layered legal invoice review model
The goal is not to choose business rules, AI, or people as a single answer. It is to route each decision to the right review layer.
Keep deterministic e-billing rules for objective controls. Use contextual AI to interpret applicable written guidance and engagement terms. Reserve human attention for the findings that require materiality, discretion, or relationship judgment.
Spend Agent is designed to complement established e-billing controls and support this layered approach. Deterministic rules handle fixed controls, contextual AI evaluates complex line-item descriptions against applicable written terms, and people make the decisions that require discretion. Together, those layers give legal teams a more governed and practical approach to invoice review.
Before you send an outside counsel RFP, your own matter records can answer six questions a law firm proposal alone cannot reliably validate: which firms have handled comparable matters, what that work actually cost, who stayed within budget, how they staffed it, whether their invoices caused problems and where consistently captured, what outcomes they delivered. Most legal departments never ask. They open the RFP process with a blank questionnaire and let the firms define the terms of the conversation.
That’s a lot of evidence to leave sitting in a system you already pay for.
What data should you review before sending an outside counsel RFP?
Which firms have handled similar matters. Marketing decks describe capability in broad strokes. Your matter records show which firms have run comparable work: same subject matter, same complexity, same jurisdictions. A practice group brochure and a track record are different things.
What comparable matters cost. Historical spend gives you a baseline you can defend. Rather than asking firms what they’ll charge in the abstract, you can weigh their pricing against what this kind of work has actually cost you. Look at the median and the range, broken out by firm. Use that history as a directional benchmark, particularly when comparing similar work across firms.
Who stayed within budget. Budget-to-actual variance is one of the most telling metrics in outside counsel management. Firms that land inside their own estimates are firms you can plan around. Firms that don’t become a source of quarterly surprises. Where your department tracks estimates and actuals consistently, use that record to inform the questions and evaluation criteria in the next RFP.
How they staffed it. Partner-to-associate ratios, team size, and how leverage shifted over the life of the matter. Cross-reference that against outcomes and cycle time and patterns start to surface. Some work rewards a lean senior team. Some doesn’t. At a minimum, ask firms to provide a clear proposed team and staffing model; where historical staffing data is available, use it as additional context.
Whose invoices caused problems. Rejected line items, out-of-guideline charges, block billing, timekeepers who never got approved. A firm’s invoice discipline can be a useful signal of the administrative burden it may create during an engagement, and guideline compliance is rarely evenly distributed across a panel.
What outcomes they produced. Wins, settlements, closings, approvals, tied to specific firms and named lead attorneys. This is the hardest of the six to capture consistently. It’s also the closest thing to a scorecard you’ll get. Where your department captures outcomes in structured fields, tie them to the responsible firm and lead attorneys.
Answer those six before an RFP goes out and the process changes shape. You stop asking firms to describe themselves and start asking them to explain the distance between what they claim and what your records show.
Why do legal departments skip their own RFP data?
For many departments, it lives in three or four places. Matter details in one system, invoices in another, budgets in a spreadsheet on someone’s desktop, outcomes in an email thread. Pulling a coherent picture together for one firm takes hours. Doing it across a panel takes weeks, and the RFP deadline rarely waits.
There’s a cultural reason too. Matter management has historically been treated as record-keeping. The idea that the same records should inform the next sourcing decision is fairly new, and it doesn’t have an obvious owner in most departments.
How do you bring matter data into the RFP process?
Standardize what you capture. Practice area, matter type, jurisdiction, staffing, budget, actual spend, cycle time, outcome. If those fields aren’t populated consistently, nothing downstream will fix it.
Let what you find set your evaluation criteria. If invoice discipline is a chronic problem across your panel, weigh it explicitly in scoring. If budget predictability is the sore spot, ask firms to defend their record on it.
Feed the results back in. Capture the same fields on the new panel. Year three of a sourcing program should look nothing like year one.
What changes in the RFP itself
Better inputs are only half of it. The evaluation has to be structured well enough to use them: standardized questionnaires so pricing arrives in a format you can line up side by side, blind review so evaluators score independently, weighted dimensions that reflect what your history says matters, and conflict questions asked the same way every time.
Structured bidding belongs in the conversation too. For defined, price-comparable work where several qualified firms are competing; a reverse auction lets them adjust pricing against anonymized rankings and produces a record of how pricing moved. It is not the right approach for every engagement; expertise, capacity, conflicts, urgency, and relationship fit should remain part of the evaluation. That record is often more useful in the CFO conversation than the final number, because it shows the competitive pressure was real.
Where this leaves you
Relationships should stay in the decision. Lawyers know things about firms that no dataset captures. But relationships alone won’t hold up when finance asks why a particular firm won a seven-figure engagement, and they won’t tell you which firm in an otherwise fine-looking panel is drifting.
Unity RFP is where that structure lives. It’s a module inside the Unity platform, working alongside matter management and e-billing rather than as a separate sourcing tool, with reusable questionnaire templates, side-by-side proposal comparison, weighted scoring with blind review, conflict-of-interest disclosures and documented responses, reverse auctions, standardized conflict-disclosure questions and documented responses, and a complete record of how the decision was made. For matter-specific RFPs, confirm the applicable rate-card, rate-transfer, and enforcement workflow before stating that negotiated rates automatically flow into Matter Management.
Legal operations teams spend countless hours reviewing invoices, enforcing billing guidelines and negotiating reductions with outside counsel. It’s an important part of managing legal spend, and one that can lead to significant cost savings over time.
But there’s a question many organizations overlook:
Can you actually prove the value of those savings?
If negotiated write-downs are tracked in email threads, spreadsheets or informal conversations, they’re difficult to measure, report on and use to demonstrate the impact of legal operations. While the savings are real, the visibility often isn’t.
For legal operations leaders, that’s a missed opportunity. It’s not enough to reduce spend. You also need to show how your team is delivering measurable business value.
Negotiating Savings Is Only Half the Battle
Most organizations have a process for reviewing outside counsel invoices. Legal teams flag billing issues, challenge questionable charges and negotiate adjustments before invoices are approved.
The problem is what happens next.
In many organizations, those negotiated reductions never make it into a centralized system. Instead, they’re documented in emails, noted in spreadsheets or simply remembered by the people involved. Over time, that creates gaps in reporting and makes it difficult to answer questions like:
How much did we save through invoice review this quarter?
Which firms consistently require adjustments?
Are our billing guidelines improving compliance over time?
Where are we seeing the greatest opportunities to reduce spend?
Without reliable data, legal operations teams are left relying on anecdotes instead of measurable outcomes.
Visibility Turns Savings Into Strategic Value
Negotiating better invoices is valuable. Being able to demonstrate that value to finance and executive leadership is even more powerful.
When savings are captured within your enterprise legal management platform, legal operations teams can:
Report on realized savings with confidence.
Identify trends across firms, matters and practice areas.
Measure compliance with outside counsel billing guidelines.
Support budgeting and forecasting conversations with accurate data.
Demonstrate the ongoing impact of legal operations initiatives.
Instead of simply saying, “We’re helping control outside counsel costs,” you can show exactly how much value your team has delivered and where that value came from.
That evidence strengthens conversations with finance, informs outside counsel strategy and gives legal operations a clearer way to demonstrate its impact on the business.
Build Savings Tracking Into Your Process
Creating better visibility doesn’t necessarily require more work. It often requires a better process.
Rather than managing invoice negotiations outside of your legal technology, consider bringing those activities into the same platform where invoices are reviewed and approved.
Some best practices include:
Capture negotiated invoice adjustments directly within your ELM platform.
Standardize invoice review workflows across the legal team.
Use billing guidelines and automated review rules to improve consistency.
Monitor trends through dashboards and reporting rather than spreadsheets.
Use historical data to benchmark outside counsel performance and inform future rate negotiations.
The goal is not simply to centralize information. It is to connect invoice adjustments with firm, matter, budget and accrual data so the legal team can understand what is driving spend and where intervention is having the greatest impact.
A Real-World Example
The RealReal, the world’s largest online marketplace for authenticated luxury resale, faced this same challenge.
Like many legal departments, the team was reviewing invoices and negotiating reductions with outside counsel. However, those write-downs were happening outside of their enterprise legal management platform, making it difficult to measure and report on the savings they were achieving.
By centralizing invoice adjustments and taking fuller advantage of their ELM capabilities, the team gained greater visibility into noncompliant charges and the savings generated through invoice review.
The team also began using data to compare requested attorney rates with similarly positioned firms and practitioners. Those insights supported outside counsel negotiations that resulted in rate reductions of 5% to 20% off standard rates for a number of firms.
The result wasn’t just better invoice management. It was a more complete understanding of outside counsel spend and more meaningful insights to support future decision making.
Want to see how they did it? Read the full The RealReal customer story to learn how the team improved visibility into legal spend and unlocked more value from its legal technology.
Proving Value Is the Next Step in Legal Spend Management
Reducing outside counsel spend is an important objective for every legal department. But today’s legal operations leaders are expected to do more than control costs. They’re expected to measure results, communicate impact and support smarter business decisions.
The organizations that stand out aren’t just the ones negotiating better invoices. They’re the ones that can clearly demonstrate the value of every improvement they make.
When savings become measurable, legal operations becomes more than an operational function. It becomes a strategic driver of business value.
For many legal departments, outside counsel selection still starts with relationships, familiar firms, and past experience.
Those factors matter. Legal work is high-stakes, and relationships can be valuable. But as legal departments face more pressure from finance, procurement, and executive leadership, the old approach is getting harder to defend on its own.
Outside counsel is often one of the largest areas of legal spend, yet many teams still lack a consistent way to compare firms, evaluate value, and manage performance after selection. T
That’s where a well-run RFP can help.
RFPs are not about replacing legal judgment with a procurement checklist. They are about giving legal teams the structure and information they need to choose the right firms for the right work.
Below, we break down five common RFP myths and what legal teams should do instead.
Myth #1: Legal RFPs Are Just a Procurement Exercise
One of the most common objections to RFPs is they exist solely to satisfy procurement requirements.
In reality, well-designed legal RFPs are strategic decision-making tools. They help legal teams gather meaningful information about a firm’s expertise, staffing approach, technology investments, pricing model, and overall fit.
The goal is not to replace legal judgment with a procurement process. It is to give legal teams the structure and insight they need to choose the right firm for the right work.
What to do instead: Position RFPs as a collaborative evaluation process focused on finding the best partner, not simply fulfilling a procurement mandate.
Myth #2: The Lowest Bidder Always Wins
Many law firms assume RFPs are simply a race to the bottom on price.
The reality is far more nuanced. RFPs are as much about information as they are about the best price.
Leading legal departments evaluate proposals across multiple dimensions, including:
Matter strategy
Relevant experience
Staffing models
Predictability
Technology capabilities
Overall value
While cost matters, it is rarely the sole deciding factor. In fact, organizations often favor firms that demonstrate the strongest overall value proposition, even when they are not the lowest-cost option.
What to do instead: Evaluate firms holistically. Focus on total value and expected outcomes rather than hourly rates alone.
Myth #3: We Already Know the Best Firms
Many legal departments rely on a small group of trusted firms they’ve worked with for years.
The challenge is that legal markets evolve quickly.
Firms develop new capabilities. Rising talent emerges. Technology investments change service delivery models. New competitors enter the market.
Even when incumbent firms ultimately retain the work, a structured RFP process often uncovers valuable information about alternative providers and reveals opportunities to improve existing relationships.
As Jason Winmill noted, the process frequently surfaces insights that legal teams simply wouldn’t have the opportunity to learn about otherwise.
What to do instead: Treat RFPs as a market intelligence exercise, not just a vendor selection exercise.
Myth #4: Formal RFPs Damage Law Firm Relationships
Some legal leaders avoid RFPs because they worry trusted firms will view them negatively.
In practice, the opposite is often true.
When handled thoughtfully, RFPs create opportunities for deeper conversations around expectations, service models, innovation, and value. They establish transparency and encourage meaningful dialogue between legal departments and their outside counsel.
The key is communication.
Law firms generally understand that legal departments face increasing pressure to demonstrate value and manage costs. A well-run process reinforces accountability without undermining trust. Additionally, modern firms are structured in a way that they now have full visibility into their data and operating models, and are positioned to partner with legal departments on something that is a win-win.
What to do instead: Focus on transparency, professionalism, and clear communication throughout the process.
Myth #5: Once the Panel Is Selected, the Work Is Done
This may be the most expensive myth of all.
Selecting outside counsel is only the beginning.
The most successful legal departments continue managing relationships after selection by establishing:
Clear scope definitions
Staffing expectations
Budget guidelines
Communication protocols
Performance metrics
Regular review cadences
Without ongoing governance, many of the benefits gained during the RFP process can quickly disappear.
As the presenters noted, selecting a firm is simply the first leg of the marathon. Real value comes from how the relationship is managed over time.
The Bottom Line
Legal RFPs are no longer just procurement exercises. They have become strategic tools that help legal departments gain valuable insights from their law firm partners, improve decision-making, strengthen outside counsel relationships, and maximize value from legal spend.
The organizations seeing the greatest success aren’t treating RFPs as one-time events. They’re using structured evaluation processes, data-driven insights, and ongoing governance to build stronger partnerships and better business outcomes.
The question is no longer whether legal departments should use RFPs. It’s whether they’re using them strategically enough.
The Uniform Task-Based Management System (UTBMS) details a series of code sets that law firms use to classify services on electronic invoices sent to clients, such as legal operations and corporate legal departments.
UTBMS codes make detailed spend reporting possible by ensuring that each task and expense is categorized. That way, when you notice in Q1 that spending is out of control, you’re able to identify and solve the problem before Q4. Of course, in order for reporting to be accurate, you must first fully understand UTBMS codes and how to use them.
The creators designed UTBMS codes to standardize the categorization of legal services and expenses so that legal work and the associated costs could be easily identified and analyzed. You can learn more about the LEDES file format and LOC at utbms.com.
UTBMS codes are used in many legal systems around the world, including the United States, Canada, and the United Kingdom. For this article, we will focus on UTBMS standards for e-Billing set by the ABA and LOC.
American Bar Association UTBMS codes
When used consistently and properly, ABA UTBMS task codes allow you to monitor legal spending and associated activities.
All ABA UTBMS codes are broken into categories and phases. Categories are identified by the beginning letter (e.g., L for ABA litigation codes) while phases are specified by the number (100s for phase 1, 200s for phase 2, etc.). While some UTBMS codes are fairly self-explanatory, others require a deeper explanation. We’ll walk you through all of the ABA UTBMS codes, and provide more insight when necessary.
Activity
Activity codes identify the type of activity associated with a cost.
A101 Plan and prepare for
A102 Research
A103 Draft/revise
A104 Review/analyze
A105 Communicate (in firm)
A106 Communicate (with client)
A107 Communicate (other outside counsel)
A108 Communicate (other external)
A109 Appear for/attend
A110 Manage data/files
A111 Other
Although not all clients require the use of UTBMS activity codes, this code set is useful for segmenting specific types of work. For instance, the four separate communication codes ensure more accurate spend tracking for both counsel and client. In situations where you may need to consult with an expert as well as outside counsel, codes A108 and A107, respectively, allow you to categorize time spent on each type of communication.
Bankruptcy
Derived from the code set published by the U.S. Department of Justice, bankruptcy UTBMS codes are intended only for bankruptcy matters. All adversarial tasks are covered by the litigation code set. The 21 bankruptcy ABA task codes are broken up into four phases.
B100 Administration
UTBMS codes in the B100 phase include administrative work during preparation, such as research, fee applications, and communication with creditors.
B110 Case Administration: Preparation of coordination and compliance matters, financial affairs statements, and general creditor inquiries
B120 Asset Analysis and Recovery: Identification and review of potential assets including causes of action and non-litigation recoveries
B130 Asset Disposition: Sales, abandonment and transaction work related to asset disposition
B140 Relief from Stay/Adequate Protection Proceedings: Matters relating to termination or continuation of automatic stay under 362 and motions for adequate protection
B150 Meetings of and Communications with Creditors: Preparing for and attending the conference of creditors, the 341(a) meeting and other creditors’ committee meetings
B160 Fee/Employment Applications: Preparations of employment and fee applications for self or others; motions to establish interim procedures
B170 Fee/Employment Objections: Review of and objections to the employment and fee applications of others
B180 Avoidance Action Analysis: Review of potential avoiding actions under Sections 544–549 of the Code to determine whether adversary proceedings are warranted
B185 Assumption/Rejection of Leases and Contracts: Analysis of leases and executory contracts and preparation of motions specifically to assume or reject
B190 Other Contested Matters (excluding assumption/rejection motions): Analysis and preparation of all other motions, opposition to motions and reply memoranda in support of motions
B195 Non-Working Travel: Non-working travel where the court reimburses at less than full hourly rates
B200 Operations
B200 codes cover business matters, such as document review, employee benefits, cash collaterals, real estate, and tax issues.
B210 Business Operations: Issues related to debtor-in-possession operating in Chapter 11 such as employee, vendor, and tenant issues and other similar problems
B220 Employee Benefits/Pensions: Review issues such as severance, retention, 401K coverage and continuance of pension plan
B230 Financing/Cash Collections: Matters under 361, 363 and 364 including cash collateral and secured claims; loan document analysis
B240 Tax Issues: Analyses and advice regarding tax-related issues, including the preservation of net operating loss carry forwards
B250 Real Estate: Review and analysis of real estate-related matters, including purchase agreements and lease provisions (e.g., common area maintenance clauses)
B260 Board of Directors Matters: Preparation of materials for and attendance at Board of Directors meetings; analysis and advice regarding corporate governance issues and review and preparation of corporate documents (e.g., Articles, Bylaws, employment agreements, compensation plans, etc.)
B300 Claims and plan
The B300 codes are used for all work related to claim inquiries and preparing disclosure statements and business plans.
B310 Claims and Administration Objections: Specific claim inquiries; bar date motions; analyses, objections and allowances of claims
B320 Plan and Disclosure Statement (including Business Plan): Formulation, presentation and confirmation; compliance with the plan confirmation order, related orders and rules; disbursement and case closing activities, except those related to the allowance and objections to allowance of claims
B400 Bankruptcy-related advice
All advice, analyses, and consultations related to bankruptcy matters fall under the B400 code set.
B410 General Bankruptcy Advice/Options: Analysis, advice and/or opinions regarding potential bankruptcy related issues, where no bankruptcy case has been filed
B420 Restructurings: Analysis, consultation and drafting in connection with the restructuring of agreements, including financing agreements, where no bankruptcy case has been filed
Counseling
Counseling is one of the broader categories of UTBMS codes. This code set is designed to cover time used by attorneys preparing to provide legal advice. Generally, the counseling ABA task codes do not attribute time to a specific matter. Instead, they serve as a catchall billing code for time spent on research throughout a monthly billing period.
C100 Fact Gathering: All initial inquiries, meetings, and data/information collection related to the assignment
C200 Researching Law: Time spent researching relevant case law or general investigation as well as consultations with experts
C300 Analysis and Advice: Analysis of work performed under C100 and C200 along with providing opinions and advice to client
C400 Third Party Communication: Discussions with third parties such as regulators or parties to contracts with the client
Expense
Expense UTBMS codes help with budget tracking by categorizing types of spending.
E101 Copying
E102 Outside printing
E103 Word processing
E104 Facsimile
E105 Telephone
E106 Online research
E107 Delivery services/messengers
E108 Postage
E109 Local travel
E110 Out-of-town travel
E111 Meals
E112 Court fees
E113 Subpoena fees
E114 Witness fees
E115 Deposition transcripts
E116 Trial transcripts
E117 Trial exhibits
E118 Litigation support vendors
E119 Experts
E120 Private investigators
E121 Arbitrators/mediators
E122 Local counsel
E123 Other professionals
E124 Other
Generally, Expense UTBMS codes are combined with a related activity code. For example, an invoice might include activity code A102 paired with expense code E101. A102 categorizes the time spent researching, while E101 specifies money spent on printing copies of that research.
This code set not only facilitates educated budget planning but also simplifies the process of submitting attorney expenses.
Litigation
ABA litigation codes are broken into five phases and encapsulate the entire litigation process.
L100 Case Assessment, Development, and Administration
L110 Fact Investigation/Development
L120 Analysis/Strategy
L130 Experts/Consultants
L140 Document/File Management
L150 Budgeting
L160 Settlement/Non-Binding ADR
L190 Other Case Assessment, Development and Administration
During the initial stages, L100 codes could be combined with activity UTBMS codes. For example, A106 (Communicate with client) might be paired with L110 or L120 because client communication would help formulate the litigation strategy.
L200 Pre-Trial Pleadings and Motions
L210 Pleading
L220 Preliminary Injunctions/Provisional Remedies
L230 Court Mandated Conferences
L240 Dispositive Motions
L250 Other Written Motions and Submissions
L260 Class Action Certification and Notice
Expense codes often accompany L200 codes, such as E112 (Court fees) associated with filing for class certification (L260) or filing a pleading (L210).
L300 Discovery
L310 Written Discovery
L320 Document Production
L330 Depositions
L340 Expert Discovery
L350 Discovery Motions
L390 Other Discovery
L400 Trial Preparation and Trial
L410 Fact Witnesses
L420 Expert Witnesses
L430 Written Motions and Submissions
L440 Other Trial Preparation and Support
L450 Trial and Hearing Attendance
L460 Post-Trial Motions and Submissions
L470 Enforcement
This phase also calls for the use of expense codes, such as E114 (Witness fees) when interviewing an expert witness (L420).
L500 Appeal
L510 Appellate Motions and Submissions
L520 Appellate Briefs
L530 Oral Argument
L600 e-Discovery
LOC and the ABA ratified the litigation codes to include a sixth phase for an e-Discovery code set. Each parent task code has sub-task codes for more granular tracking. To keep this brief, we’ll list only the parent tasks.
L600 Identification
L610 Preservation
L620 Collection
L630 Processing
L650 Review
L660 Analysis
L670 Production
L680 Presentation
L690 Project management
Project
For non-litigation matters, project codes are used for administrative filings, transactions, and stand-alone projects. The project code set includes eight phases.
P100 Project Administration: All initial administration work such as developing, negotiating, and revising the plan and budget for the matter at hand
P200 Fact Gathering/Due Diligence
Codes within the P200 phase are used for time spent on fact investigation, document retrieval, and preparation of reports with clients. They also cover coordination with third parties related to these activities.
Each P200 UTBMS code designates time spent on fact investigation/due diligence from a specific perspective, such as tax or environmental.
P210 Corporate Review
P220 Tax
P230 Environmental
P240 Real and Personal Property
P250 Employee/Labor
P260 Intellectual Property
P270 Regulatory Reviews
P280 Other
P300–P800 make up the additional codes within this phase.
P300 Structure/Strategy/Analysis: Time spent on analysis done for the purposes of developing the strategy for a project or transaction. This includes all steps taken to create a written outline or description of the strategy
P400 Initial Document Preparation/Filing: Tasks performed to prepare documents and opinions before being sent to third parties. This includes filing documents, related communications with the client, and review of client-generated transaction documentation
P500 Negotiation/Revision/Responses: Time spent negotiating and revising P400 transaction documentation, including all related document review, meetings, and client communications
P600 Completion/Closing: All tasks related to transaction pre-closing and closing, project completion or filing acceptance, such as attendance at closing
P700 Post-Completion/Post Closing: All post-completion or post-closing tasks such as amendments to final documentation and resolution of post-closing issues. Also includes all implementation tasks (e.g., funds held in escrow) and preparation of closing binders (i.e., primarily clerical actions)
P800 Maintenance and Renewal: All tasks related to subsequent maintenance and renewal requirements under the terms of the transaction or project such as monitoring of lease agreements, routine waivers and coordination of UCC requirements
Workers’ compensation
A 2010 ratification defined the workers’ compensation code set. Many tasks include a “Commentary & Practice Tips” subset that shares the same code as the parent task. For example, WC 110 could refer to Fact Investigation/Development or the Commentary & Practice Tips related to that task.
This UTBMS code set includes a total of five phases and 27 ABA task codes. For the sake of brevity, we will provide a high-level description of each phase. It’s important to note that the Workers’ Compensation code set does not include phase-level parent tasks (WC 100, WC 200, WC 300, etc.)
WC 100 phase
All actions related to researching the case matter, strategizing, consulting with experts, and settlements.
WC 110 Fact Investigation/Development
WC 110 Commentary & Practice Tips
WC 120 Analysis/Strategy
WC 120 Commentary & Practice Tips
WC 130 Experts/Consultants
WC 130 Commentary & Practice Tips
WC 150 Budgeting
WC 150 Commentary & Practice Tips
WC 160 Settlement/Resolution
WC 160 Commentary & Practice Tips
WC 180 Alternative Fee Arrangements
WC 200 phase
Time spent preparing and filing pleadings, conferences with judge, and negotiating alternative fee arrangements.
WC 210 Pleadings
WC 210 Commentary & Practice Tips
WC 230 Conferences with Judge
WC 230 Commentary & Practice Tips
WC 280 Alternative Fee Arrangements
WC 300 phase
Time spent on all discovery motions, document production/acquisition, and depositions.
WC 310 Written Discovery
WC 310 Commentary & Practice Tips
WC 320 Document Production/Acquisition
WC 320 Commentary & Practice Tips
WC 330 Depositions
WC 330 Commentary & Practice Tips
WC 334 Deposition Report
WC 340 Expert Discovery
WC 340 Commentary & Practice Tips
WC 350 Discovery Motions
WC 350 Commentary & Practice Tips
WC 360 Discovery On-Site Inspections/Visits
WC 360 Commentary & Practice Tips
WC 380 Alternative Fee Arrangements
WC 400 phase
Time spent preparing for and communicating with witnesses, drafting written motions, and preparing for and attending hearings.
With Onit, you can process invoices using UTBMS codes to help your team better categorize outside counsel activity and track spend at a more granular level. Additionally, you can also configure custom task, activity, and expense codes if your department leverages them.
When invoices are categorized, you can run standard or ad-hoc reports for matter-level comparisons of legal spend by task code, as well as other insights. This insights include views into spend by task for your practice areas or specific vendors. Onit also provides a Spend Dashboard that quickly identifies your top task codes in use, along with information about average rates and how much was billed to each code.
UTBMS codes also allow you to enforce billing guidelines and control spending. You can set limits and create warnings associated with specific codes so that expenses can be automatically approved, rejected, or adjusted… all within a single platform.
Start using UTBMS codes to streamline legal spend management
Stop digging for codes every time a question comes up. This reference guide puts the most important UTBMS and ABA codes in one place so your team can use them quickly and confidently. Download the UTBMS & ABA Codes Reference Guide
Of course, knowing the codes is one thing. Getting your team to use them correctly is another. This checklist shows you exactly how to implement and maintain coding standards across matters and vendors. Get the UTBMS & ABA Codes Implementation Checklist
Accurate UTBMS coding is the foundation of effective legal spend management. When every task and expense is properly categorized, your team gains the visibility it needs to enforce billing guidelines, identify inefficiencies, and make informed decisions about outside counsel spend.
Vendor relationships don’t fail because of bad intentions. They fail because the vendor management systems Legal teams use to deal with outside counsel create friction, inconsistency, and information gaps that erode trust on both sides.
Legal departments spend significant time selecting outside counsel, negotiating rates, and setting expectations. Yet many of those same departments track vendor performance through scattered notes, manage billing disputes over email, and make staffing decisions based on anecdotal memory rather than structured data. The consequences compound quietly until a budget surprise or a stalled matter forces the issue into the open.
Strong vendor relationships aren’t built through better communication alone. They’re built through operational systems that make expectations clear, performance visible, and decisions defensible.
When vendor management lives in someone’s inbox
Manual vendor management creates a specific kind of risk: the risk of institutional knowledge walking out the door. When performance history, rate agreements, and matter outcomes exist only in email threads or spreadsheets tied to one person, the entire vendor relationship becomes fragile.
Teams lose continuity when a matter transitions between team members. Rate exceptions approved informally become precedents nobody can trace. Billing disputes require reconstructing context that should have been captured automatically. Outside counsel receives inconsistent signals about what’s expected because enforcement depends on who’s reviewing invoices on any given week.
Without structured data, vendor decisions revert to familiarity rather than evidence. The firm that gets work isn’t always the firm that performs best. It’s often the firm that’s easiest to reach or the one a senior attorney worked with years ago. That’s not vendor management. That’s managed chance. As we’ve noted in our writing on 9 manual legal tasks your team needs to stop doing immediately, managing vendors through inboxes and memory is one of the most common and costly habits holding Legal departments back.
What does structured vendor data actually include?
Structured vendor management captures rate history, matter outcomes, billing guideline compliance, timekeeper performance, and outside counsel spend by matter type in a centralized system. This data allows Legal teams to evaluate vendor relationships objectively rather than relying on recollection or relationships.
Billing guidelines only work when they’re enforced consistently
Most Legal departments have outside counsel billing guidelines. Fewer enforce them systematically. When enforcement depends on manual review, guidelines become aspirational rather than operational.
Manual invoice review introduces variability by design. Reviewers apply guidelines differently based on their familiarity with the matter, the volume of invoices in their queue, and the informal norms that develop when guidelines aren’t embedded in the review process. Over time, outside counsel learns where the lines bend, and billing behavior adjusts accordingly.
The operational cost is significant. Billing violations that aren’t flagged before approval become approved spend. Disputes raised after payment create friction in the vendor relationship and rarely result in full recovery. And the pattern repeats because nothing in the system prevents it.
Automated billing review changes this by making enforcement consistent and proactive. When billing rules are built directly into the review process, violations surface before approval rather than after. The conversation with outside counsel shifts from retroactive correction to shared expectation. That shift reduces friction, improves compliance, and builds a more predictable foundation for the relationship. Our analysis of legal eBilling ROI shows that AI-driven review tools identify overbilling and enforce guidelines before invoices reach approval, creating a process that’s both faster and more defensible.
Visibility gaps affect both sides of the relationship
Outside counsel wants clarity too. Firms that submit invoices without knowing whether guidelines were met, whether payments are progressing, or whether the matter is trending toward budget problems operate with the same information gaps that frustrate internal teams.
When Legal departments lack real-time visibility into matter spend and status, they can’t provide outside counsel with meaningful feedback until problems are already significant. Budget conversations happen late. Rate discussions lack grounding in actual performance data. Staffing decisions rely on general impressions rather than objective metrics.
Legal departments that provide outside counsel with clear expectations, consistent feedback, and structured performance data build more productive relationships with their vendors. Firms that understand what’s being measured and how decisions are made can actually respond to those expectations. This is the core argument behind modern legal operations: visibility isn’t a reporting problem. It’s a relationship problem that structured systems solve.
Trust is built through operational consistency, not relationship management
The framing of vendor management as a relationship skill understates the structural problem. Trust between Legal departments and outside counsel is an outcome of consistent, transparent operations, not a product of goodwill or tenure.
When billing guidelines are enforced the same way every time, outside counsel can plan around them. But when performance data is tracked objectively across matters, firms receive feedback they can act on. And if matter status and spend are visible in real time, both sides operate from shared information rather than competing assumptions.
The legal spend spiral that many Legal departments experience, where costs drift upward through small, unnoticed exceptions, is often a vendor management failure before it’s a budget failure. Rate exceptions become routine. Scope creep goes unaddressed. Billing behavior adjusts to what gets approved rather than what guidelines require. Catching those signals early requires systems that surface patterns, not just people who notice problems.
What operational consistency looks like in practice
Consistent vendor management means billing rules are embedded in the review process, not reviewed after the fact. It means timekeeper rates are validated against approved schedules before invoices are processed. It means matter budgets are established at opening and tracked continuously, so outside counsel has real-time context for staffing and scope decisions.
Performance data changes the vendor conversation
When Legal departments track vendor performance objectively, the conversation with outside counsel changes from qualitative to quantitative. Instead of general impressions about quality or responsiveness, teams can discuss specific metrics: billing compliance rates, matter cycle times, cost per outcome by matter type, and timekeeper utilization against budget.
That shift matters because it gives outside counsel something concrete to respond to. Firms that understand how they’re being evaluated, and what data is driving those evaluations, can adjust staffing, improve billing practices, and align their work more closely with what the Legal department actually needs. Firms that operate without that feedback can only guess.
Vendor selection improves through the same mechanism. When historical performance data is accessible and structured, decisions about which firms receive work are grounded in evidence rather than relationships. That’s better for the Legal department, and it’s better for the vendors that consistently deliver results.
Making vendor relationships a system output, not a management task
Vendor relationships don’t sustain themselves through effort alone. They sustain through systems that make performance visible, expectations clear, and decisions consistent over time.
Legal departments that treat vendor management as an operational capability, rather than a relationship function, gain leverage in negotiations, confidence in budget forecasts, and credibility with finance and leadership. The data generated through structured vendor management becomes the foundation for every conversation about outside counsel spend, staffing, and performance.
Understanding where your current vendor management process creates the most friction is the right place to start.
These are the questions you should be asking:
Does performance data exist in a system, or in someone’s memory?
Are billing guidelines enforced before approval, or disputed after the fact?
Are matter budgets tracked continuously, or reconciled at quarter end?
Answering those questions honestly reveals where operational investment delivers the most immediate return.
If you want to quantify what better vendor management could mean for your department’s budget and efficiency, Onit’s ROI Calculator gives you the data to make that case to leadership.
Jasmine Sims put it plainly during the discussion.
When budgets are tight, the fastest way to unlock technology investment is to fix inefficient processes first.
Because good technology cannot repair a bad process.
Legal ops leaders who understand this sequence focus on operational clarity first. Then they automate.
Where AI Actually Helps
There’s another assumption that slows progress in legal departments. That AI will replace lawyers.
It won’t.
The legal profession runs on judgment.
Lawyers interpret context. Assess risk. Make decisions with accountability.
AI does something different. It removes the low-judgment work.
Reviewing standard clauses.
Scanning large contract portfolios.
Identifying patterns across thousands of documents.
That’s where AI shines. Humans define the decisions, AI helps them get there faster while still allowing them the oversight that keeps them comfortable.